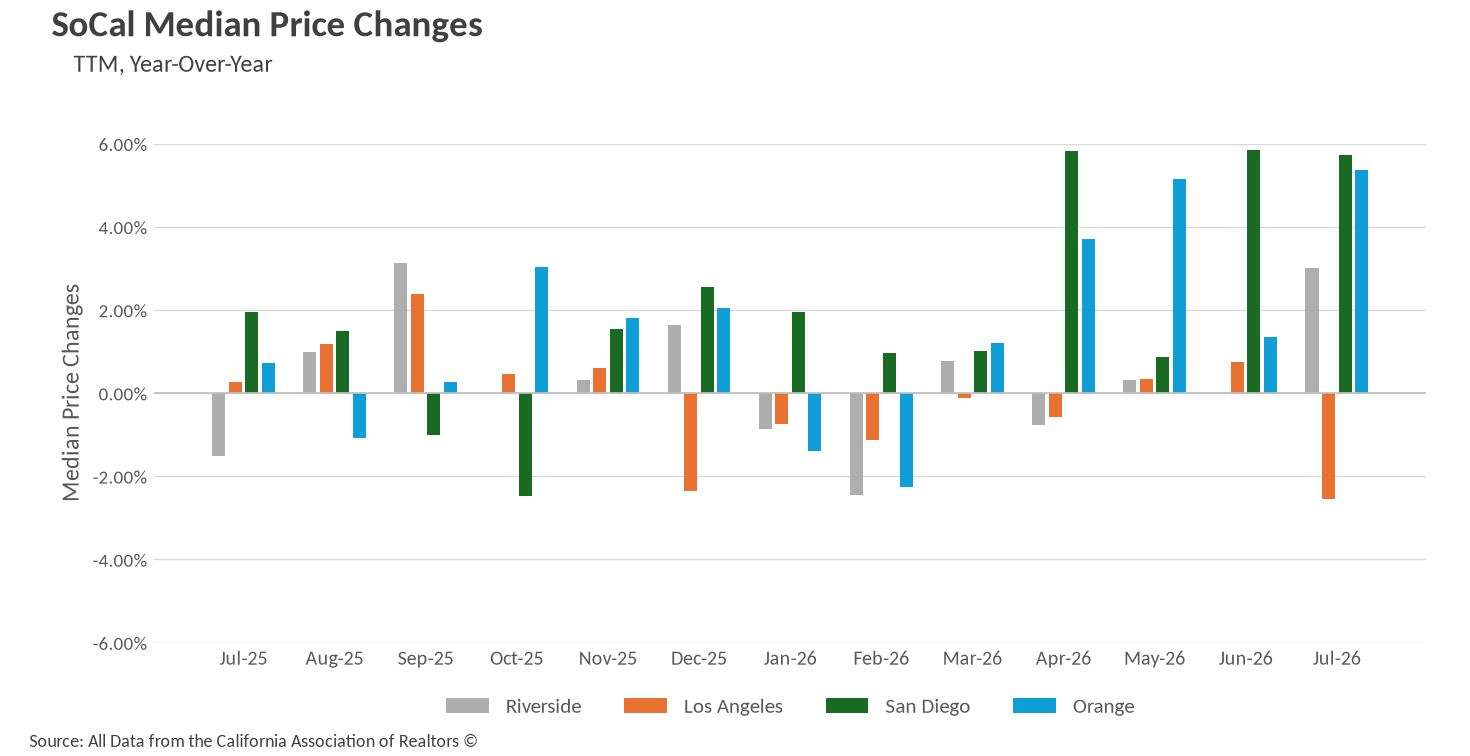Market Update Los Angeles
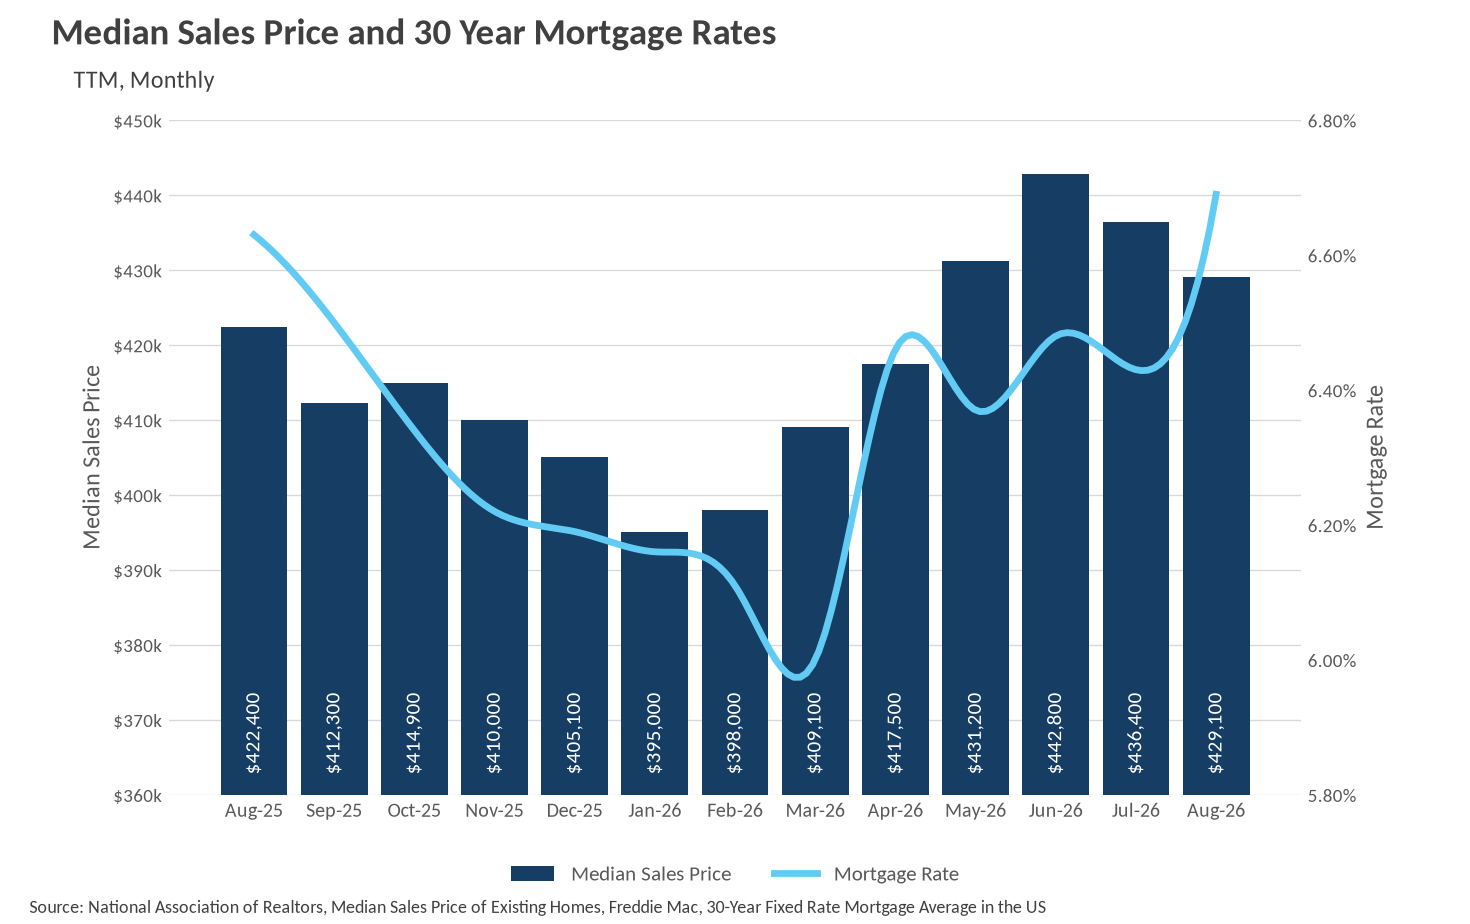
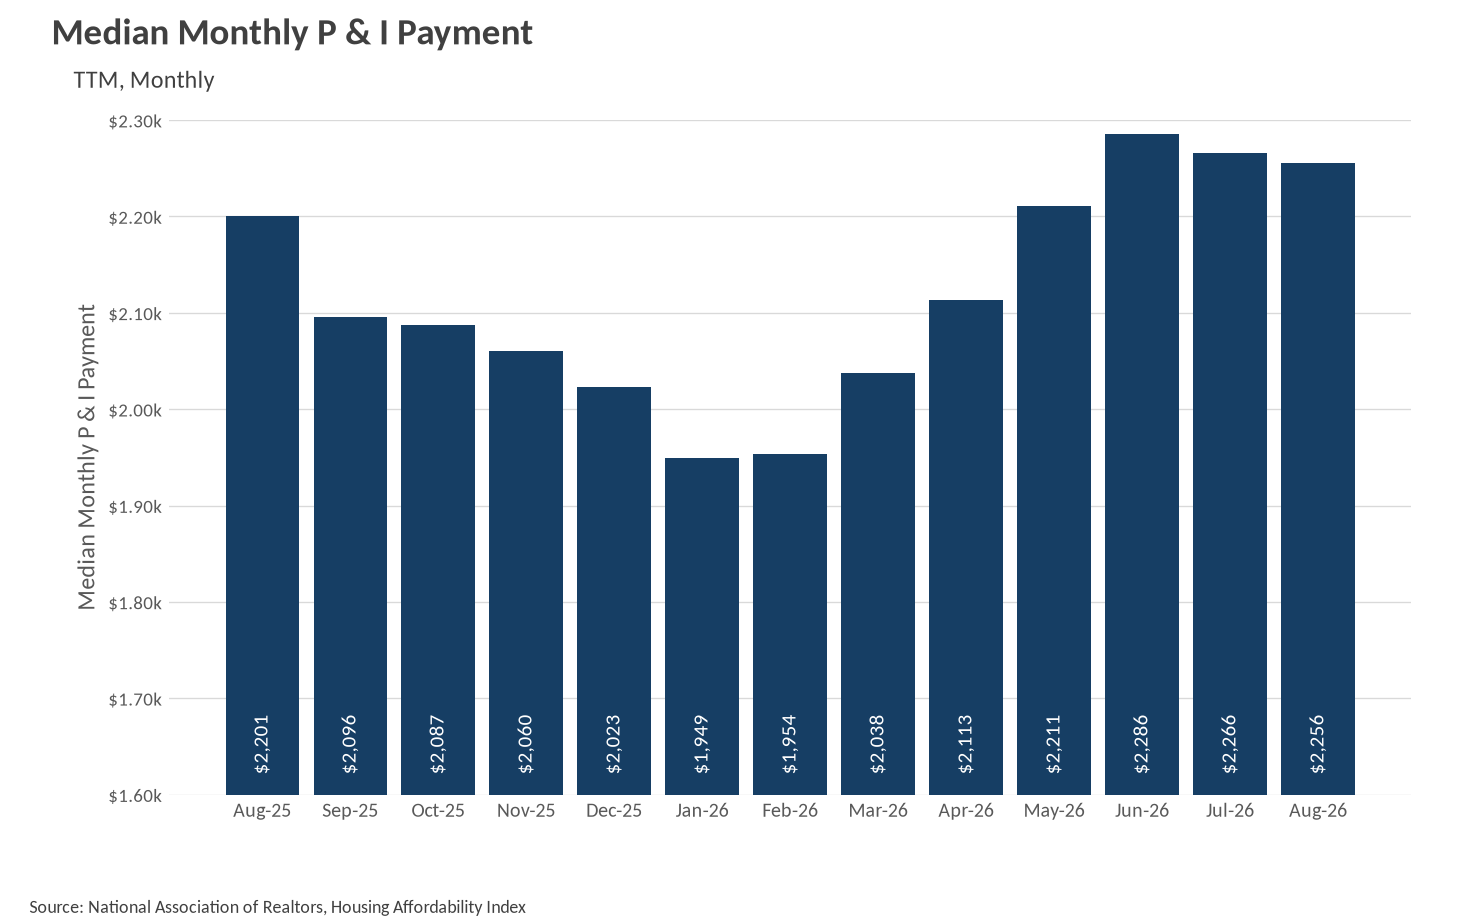
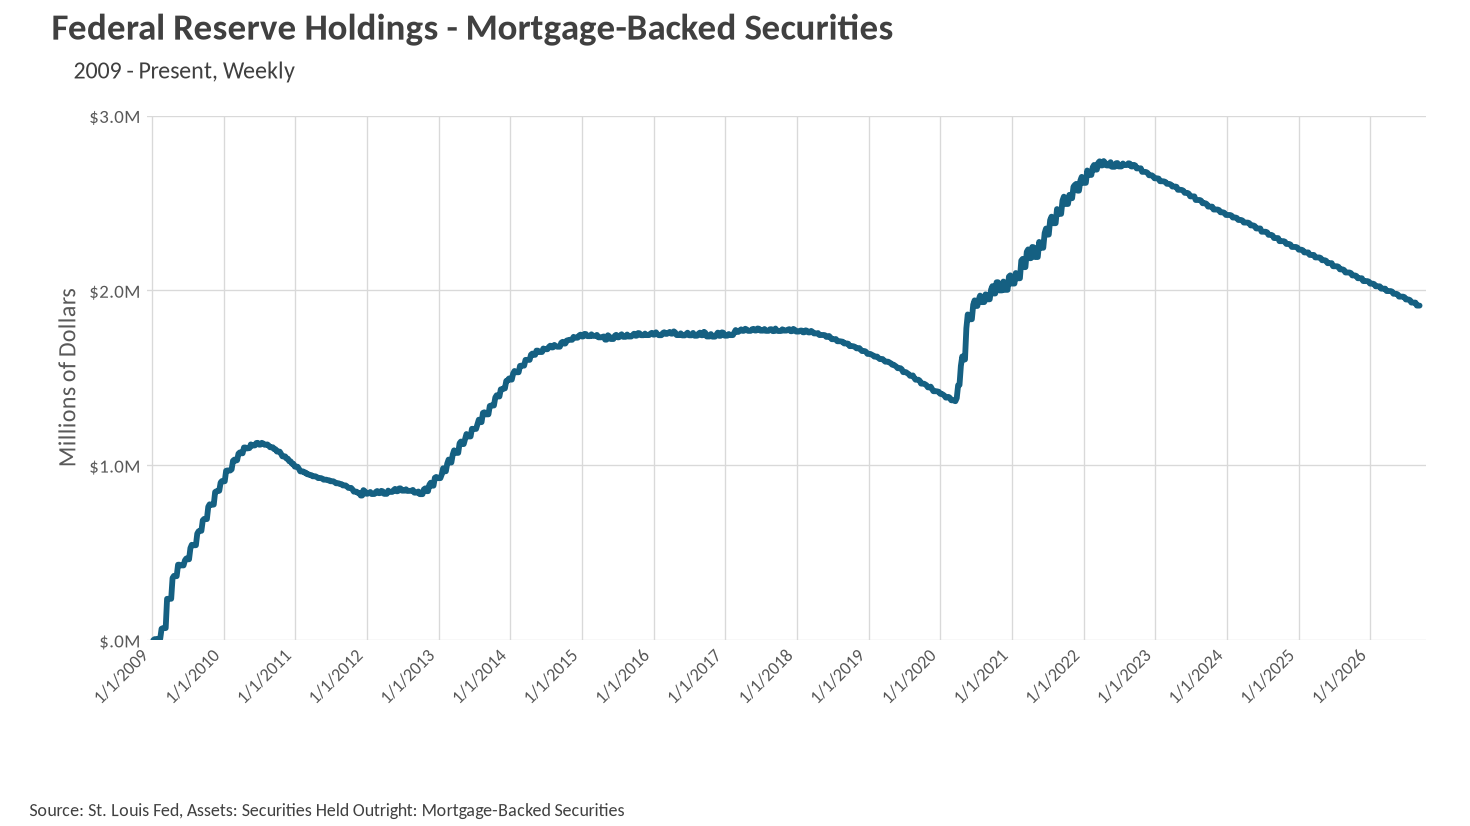
After five straight months of gains carried the median sale price to $442,800 in June, prices have now declined in each of the past two months. In August, the median home sold for $429,100, a 1.67% month-over-month decline from July's $436,400 and a 3.09% pullback from the June peak. The one bright spot is that prices are still running 1.59% above the $422,400 median we saw in August of last year, so the year-over-year comparison remains positive even as the seasonal momentum fades. The affordability story, however, has turned decisively less friendly. Mortgage rates jumped to 6.69% in August and edged up again to 6.71% in September, the highest readings in this entire data series and a full 71 basis points above the 6.00% low we saw back in March. The median monthly principal and interest payment now sits at $2,256, which is 2.50% higher than the $2,201 buyers were paying a year ago and more than $300 above the $1,949 January low. In other words, the affordability cushion that lower rates provided at the start of the year has now been completely erased. It is also worth noting that the Federal Reserve's mortgage-backed securities holdings have continued to run off, declining from roughly $2.05 trillion at the end of last year to about $1.91 trillion in September, which removes a meaningful source of demand for mortgage debt and helps explain why rates have been drifting higher even as the broader market cools.
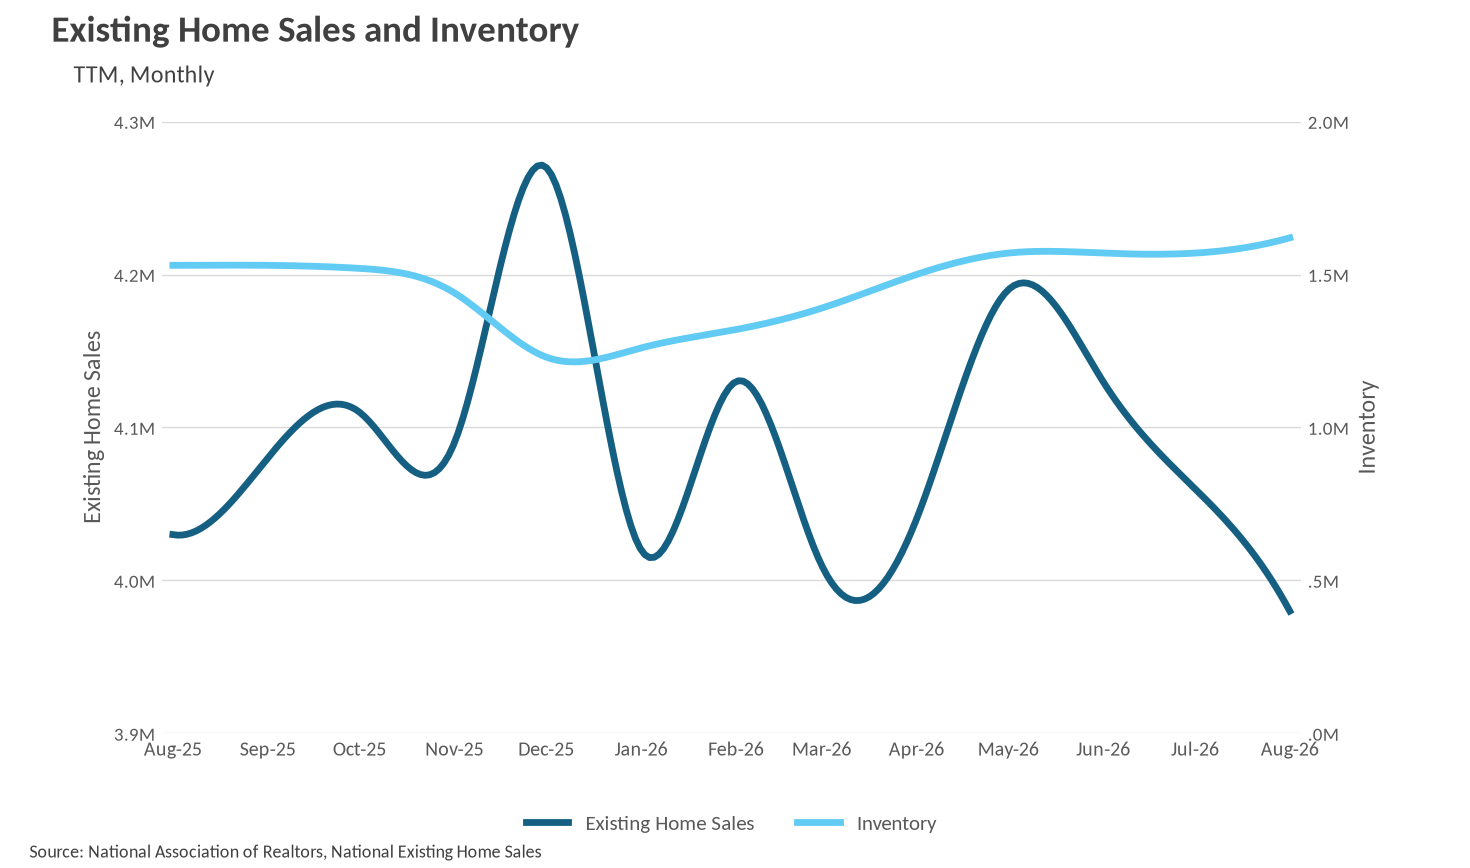
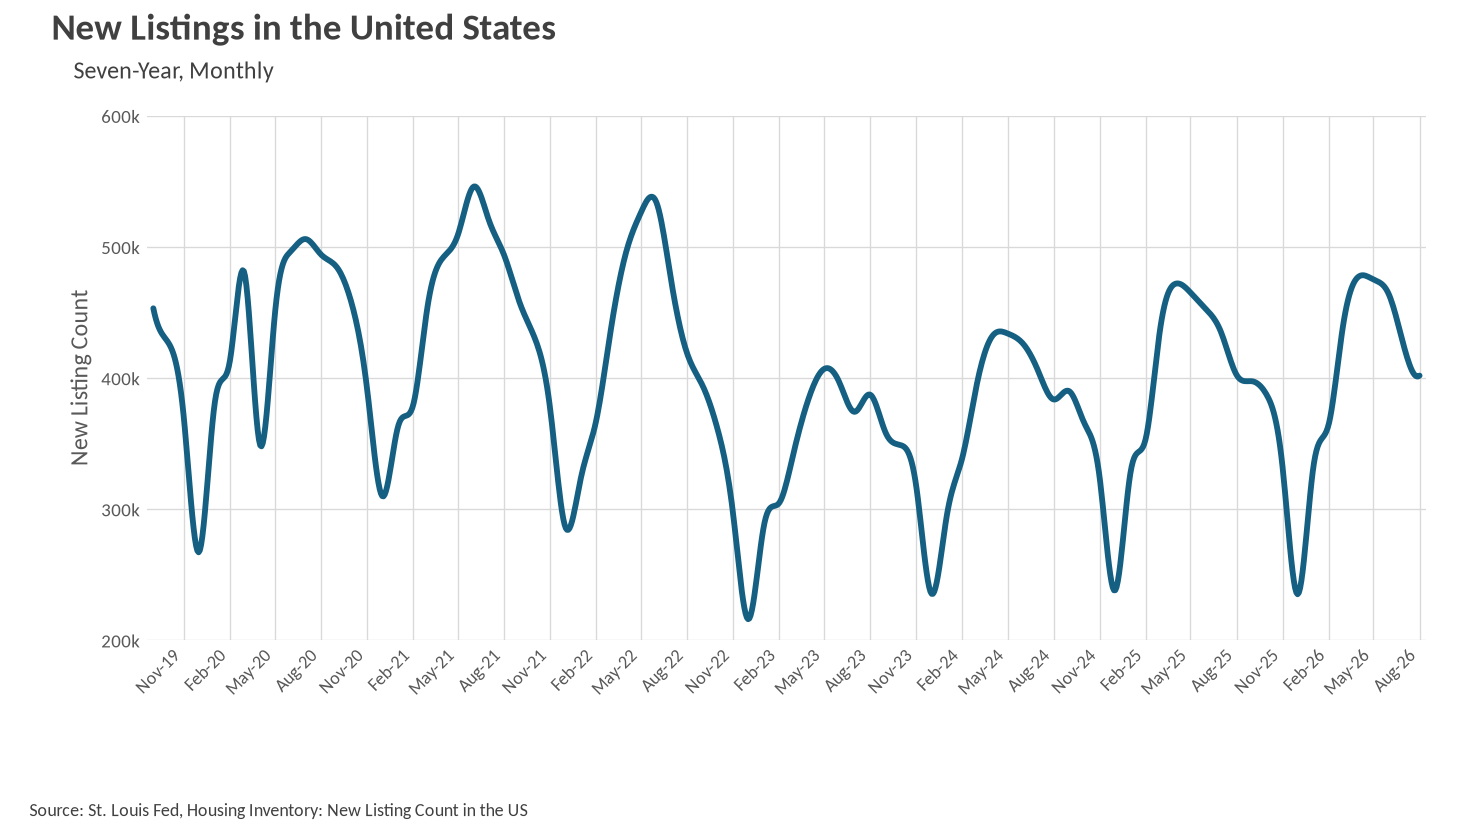
Inventory did not plateau after all. After holding flat at 1,570,000 homes for three consecutive months from May through July, inventory jumped to 1,620,000 in August, a 3.18% month-over-month increase and a 5.88% gain over the 1,530,000 homes available at this time last year. That is the highest inventory level anywhere in this data series, and it represents a 31.7% increase from the December low of 1,230,000. What makes this build particularly notable is that it is not being driven by a flood of new supply. New listings actually fell to 401,760 in August, down 5.18% from July's 423,732 and essentially flat compared to the 402,276 new listings we saw in August of last year. So sellers are not listing more aggressively than they were a year ago. Instead, inventory is accumulating because homes are not clearing at the pace they once did. That distinction matters, because supply that builds from weak absorption tends to be stickier and puts more direct pressure on pricing than supply that builds from a surge of eager sellers.
Existing home sales came in at 3,980,000 in August, a 1.97% month-over-month decline from July's 4,060,000 and a 1.24% drop from the 4,030,000 pace we saw in August of last year. This is the weakest sales figure in the data we have, and it marks a clear reversal from the spring, when sales were running above the prior year and reached 4,190,000 in May. The culprit is not hard to identify. Buyers who were enjoying sub-$2,000 monthly payments in January are now looking at $2,256, and mortgage rates that started the year at 6.16% are now sitting at 6.71%. When financing costs move that much in nine months, the marginal buyer simply steps out of the market, and that is exactly what the sales data is showing. Three consecutive months of declining sales, combined with inventory pushing to new highs, tells us that the balance of the market has shifted in a way it had not through the first half of the year. The question now is whether rates stabilize and let buyers re-engage this fall, or whether we continue to see demand erode into the winter.
When determining whether a market is a buyers’ market or a sellers’ market, we look to the Months of Supply Inventory (MSI) metric. The state of California has historically averaged around three months of MSI, so any area with at or around three months of MSI is considered a balanced market. Any market that has lower than three months of MSI is considered a seller’s market, whereas markets with more than three months of HSI is considered buyers’ markets.
At the national level, the numbers point clearly toward a buyers' market. With 1,620,000 homes for sale in August against an annualized sales pace of 3,980,000, the implied months of supply works out to roughly 4.9 months, comfortably above the three-month threshold that separates balanced markets from buyers' markets. A year ago, that same calculation produced about 4.6 months, so supply has loosened meaningfully over the past twelve months. Every component of the equation is currently moving in buyers' favor: inventory is at a cycle high and rising, sales are falling on both a monthly and annual basis, and median prices have declined for two straight months. The obvious catch is affordability. Buyers may have more negotiating room and more homes to choose from than at any point in recent memory, but with rates at 6.71% and monthly payments up more than $300 since January, the cost of taking advantage of that leverage has risen sharply. Sellers, for their part, should expect longer marketing times and more price sensitivity than they saw this spring. As always, real estate is a highly localized asset, which is why you should check out what's going on in your local market below in the Local Lowdown!
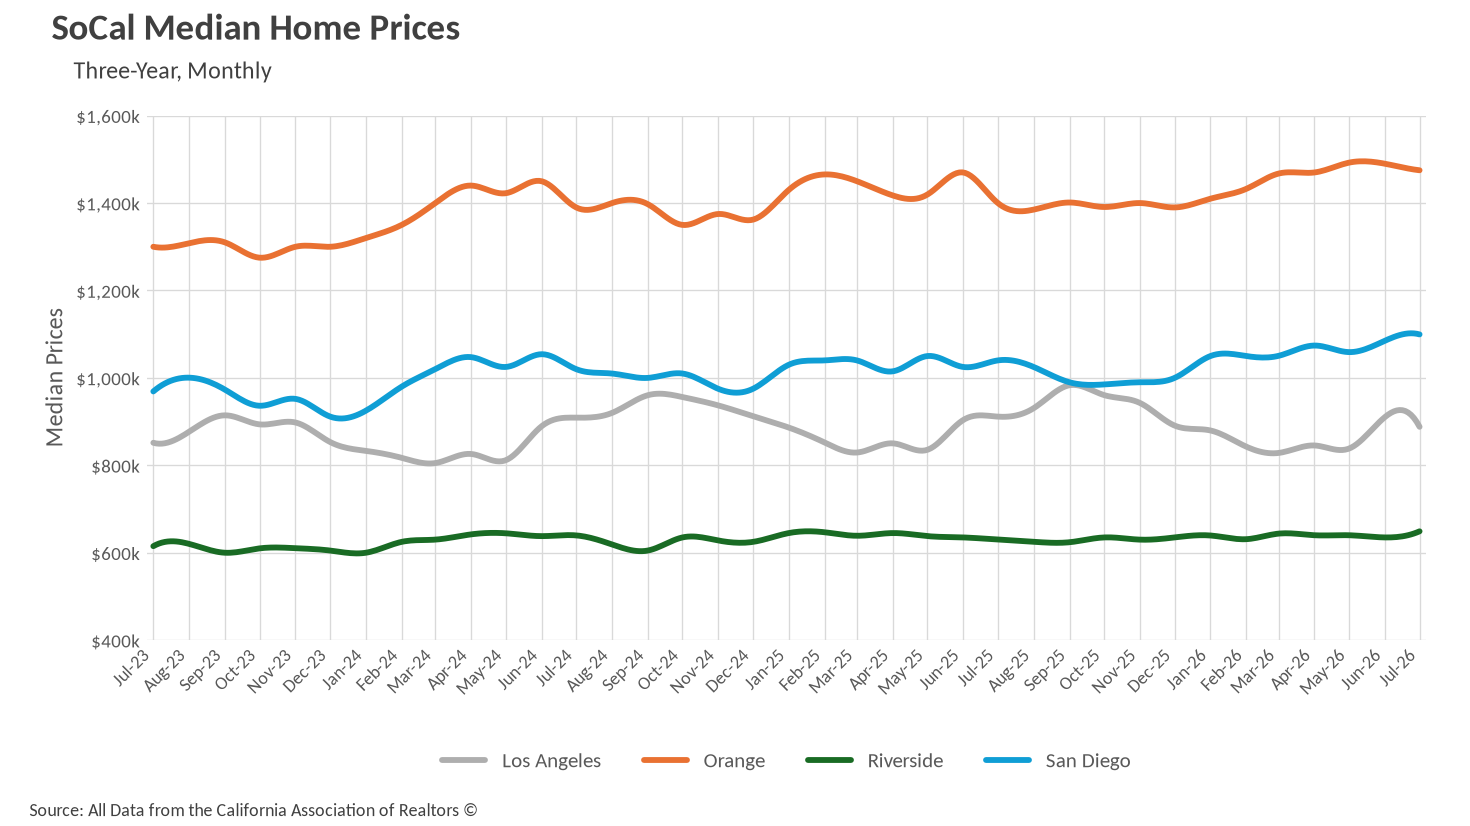
The headline story across Southern California this July is one of broad-based appreciation with a single notable exception. San Diego set a new high for our data series at $1,099,500, a 5.72% year-over-year gain and the tenth consecutive month of growth for that market. Orange County was right behind it, with a $1,475,000 median that represented a 5.36% jump over last July and the strongest year-over-year reading the county has produced all year. Riverside quietly joined the party, posting a $649,000 median that is up 3.02% from the $630,000 recorded last July and, notably, the highest figure anywhere in our Riverside series, surpassing the $646,840 peak set back in February 2025. Riverside also managed a 2.20% month-over-month gain from June's $635,000, bucking the mild summer pullbacks seen in Orange County and Los Angeles.
Los Angeles is the outlier. After modest year-over-year gains in May and June suggested the county had turned a corner, July's $888,120 median landed 2.55% below last July and 2.44% below June. The county remains roughly 9.7% off its September 2025 high of $983,230, and while the reading is still well above March's $828,300 trough, Los Angeles pricing has largely been trading sideways for a year while its neighbors have pushed to new highs. Taken together, the region's price map now looks less uniform than it did twelve months ago, with the coastal south and the Inland Empire firming while the region's largest market catches its breath.
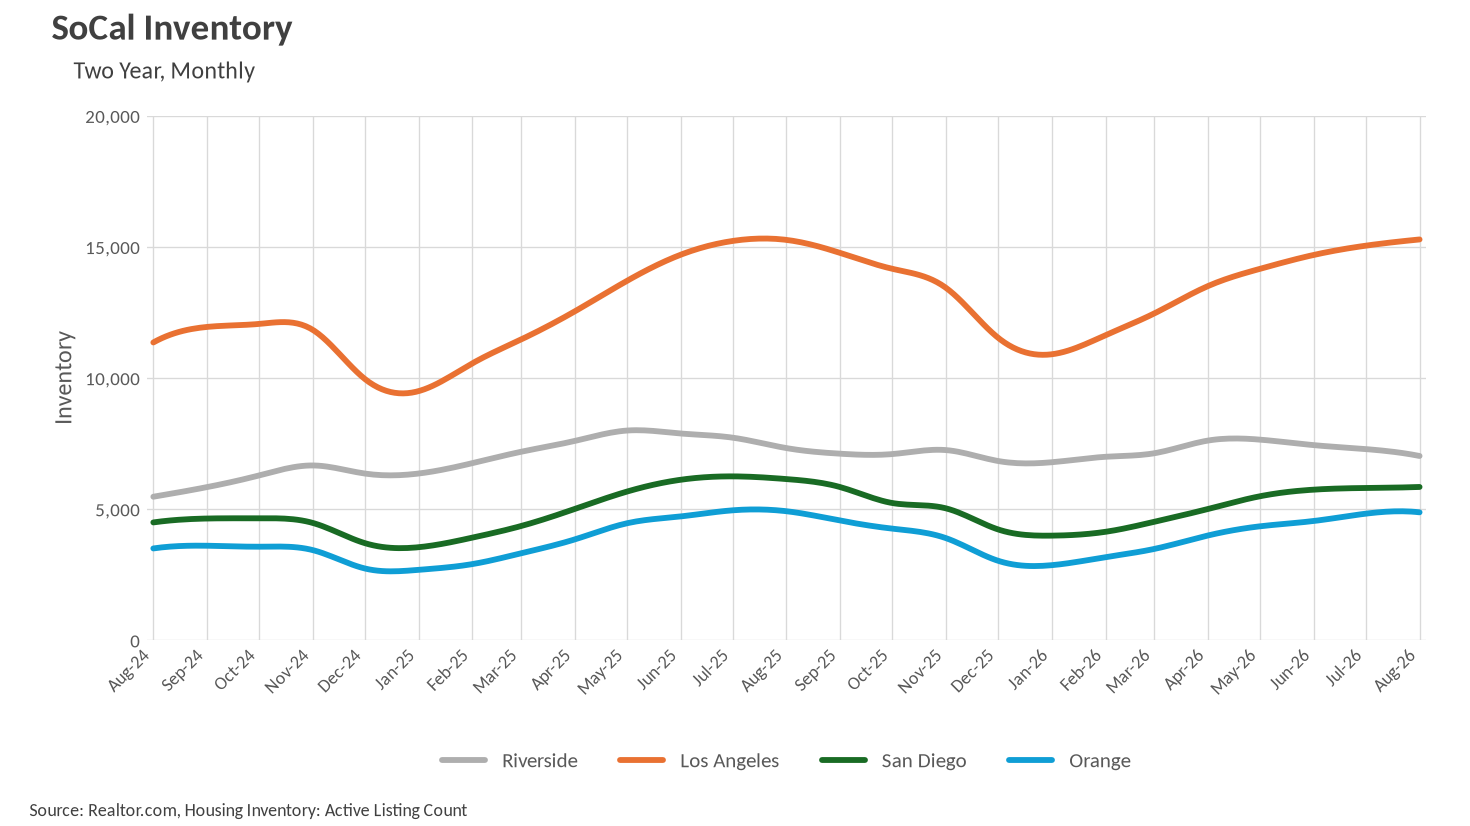
August inventory readings, which run a month ahead of our other metrics, tell a consistent regional story: the supply glut that shaped much of 2025 has not returned. Across the four counties, there were roughly 33,000 active single-family listings in August, about 1.9% fewer than the same month last year. San Diego led the contraction at 5,841 listings, down 4.90% year over year and the fifth straight month of declines there. Riverside was close behind at 7,023 listings, a 4.10% year-over-year drop and a 3.60% decline from July, marking its third consecutive monthly decrease from May's peak of 7,646. Riverside has now trailed year-ago inventory for four straight months after running even with or ahead of 2025 earlier in the year.
Orange County's 4,874 listings represented its highest count of 2026, yet still came in 0.85% below last August, the fourth consecutive month under year-ago levels. Los Angeles is the only market where supply has fully caught up, with 15,279 listings in August sitting a nearly imperceptible 0.11% above last year and at the county's 2026 high. The common thread is deceleration. Orange County's month-over-month growth slowed to 1.06%, San Diego's to 0.65%, and Riverside actually reversed course. Sellers heading into fall are, with the partial exception of Los Angeles, facing less competition than their counterparts did a year ago.
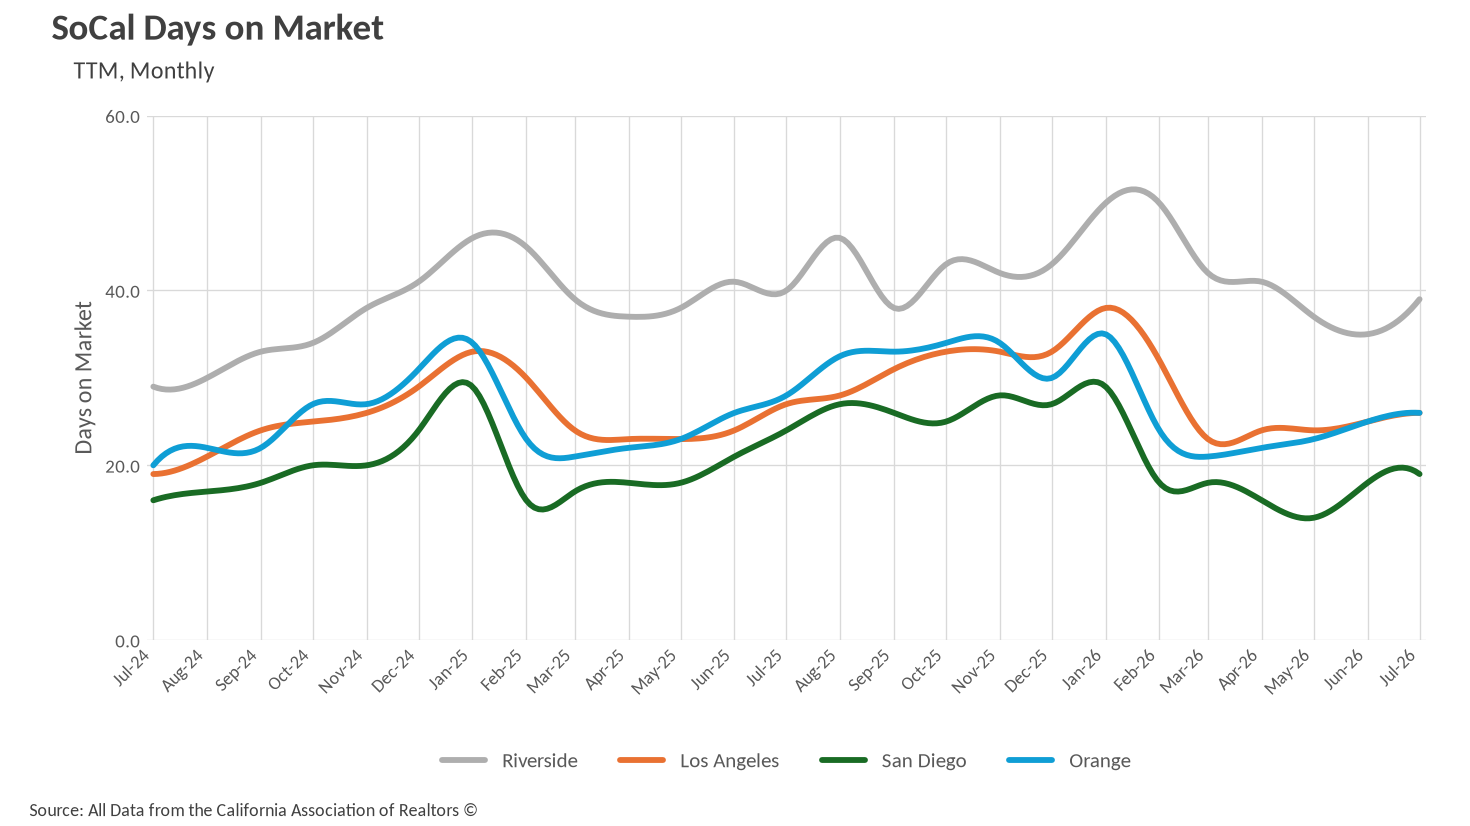
Days on market improved year over year in all four counties, which is the single most consistent data point in this month's numbers. San Diego remains the region's quickest market by a wide margin at 19 days, a 20.83% improvement over the 24 days it took last July. Los Angeles and Orange County were effectively tied at 26 days, down 3.7% and 7.14% respectively. Riverside is the slowest of the group at 39 days, but even there the trend is favorable, with July's reading coming in a day faster than last July's 40 and dramatically better than the 50 days recorded in both January and February.
All four counties did see a modest seasonal uptick from June, which is normal as the spring urgency fades. Los Angeles and Orange County each ticked up from 25 days, San Diego from 18, and Riverside from 35. Riverside's four-day move is the largest of the group, and it is worth watching given that last year the county deteriorated sharply through late summer, hitting 46 days in August. For now, the regional picture is one of buyers who are taking slightly more time than they did in the spring but still moving decisively, a meaningful counterweight to the softer pricing data out of Los Angeles.
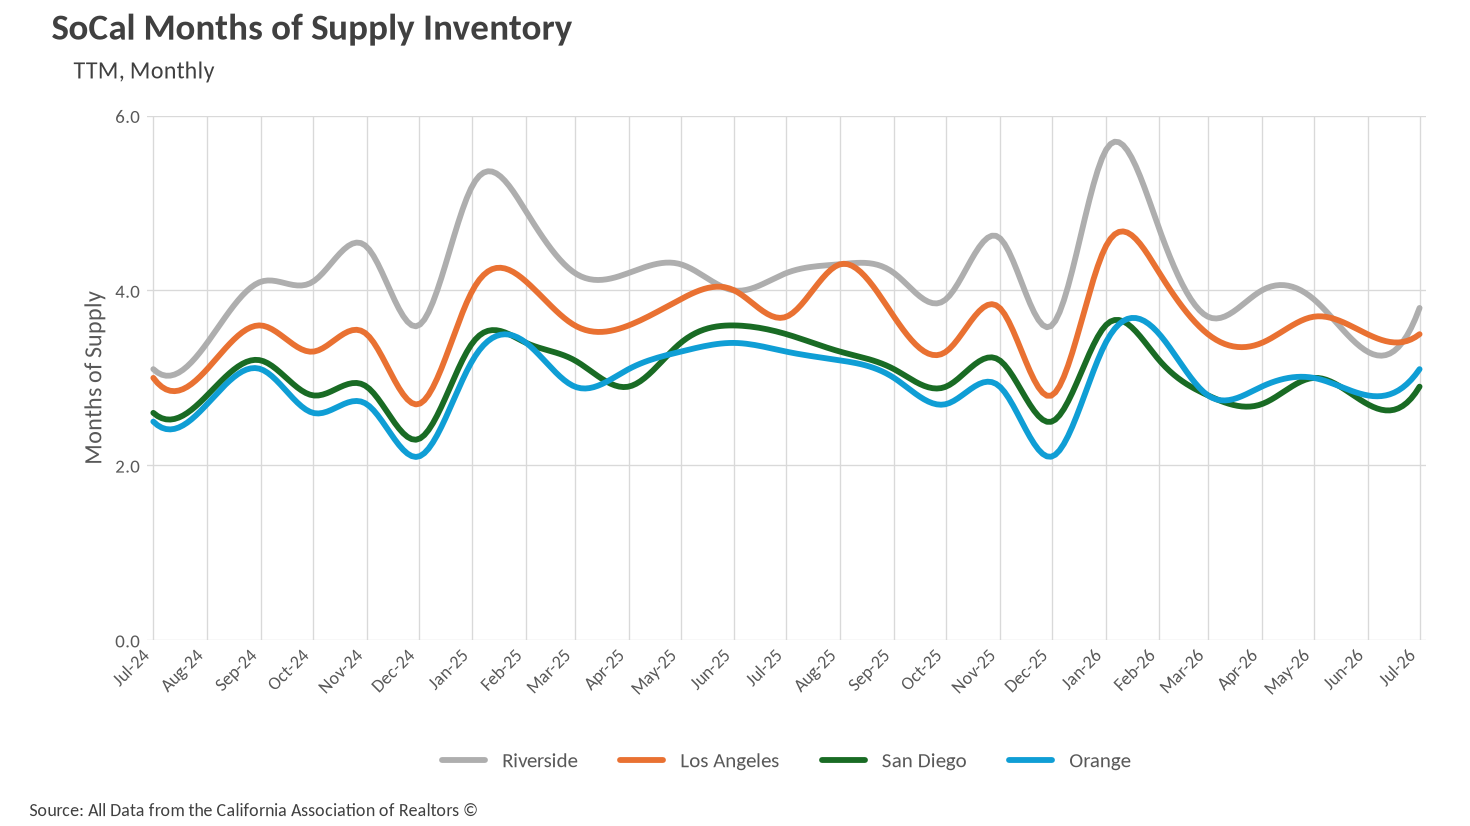
When determining whether a market is a buyers’ market or a sellers’ market, we look to the Months of Supply Inventory (MSI) metric. The state of California has historically averaged around three months of MSI, so any area with at or around three months of MSI is considered a balanced market. Any market that has lower than three months of MSI is considered a seller’s market, whereas markets with more than three months of MSI are considered buyers’ markets.
Southern California's four major counties averaged roughly 3.3 months of supply in July, placing the region as a whole in balanced territory with the faintest tilt toward buyers. The internal spread is where the nuance lives. San Diego, at 2.9 months, is the region's only true seller's market, down 17.14% from the 3.5 months it carried last July. Orange County sits at 3.1 months, squarely balanced and down 6.06% year over year. Los Angeles holds 3.5 months, unchanged from June and down 5.41% from last year, putting it modestly into buyers' territory without feeling lopsided. Riverside remains the region's most buyer-friendly market at 3.8 months, though that figure is down 9.52% from the 4.2 months on hand last July and a world away from January's 5.6 month spike.
The unifying point is that every one of these markets is carrying less supply than it was twelve months ago, and every one is selling homes faster. That combination is what typically precedes firming prices, and it is already showing up in San Diego, Orange County, and Riverside. Buyers still have genuine negotiating room, particularly in Riverside and in Los Angeles listings priced off the fall 2025 highs, but if the normal autumn inventory decline plays out on schedule, the balance of leverage across the region is likely to keep sliding toward sellers through the end of the year.
Stay up to date on the latest real estate trends.
October 2026
September 2026
August 2026
July 2026
A Closer Look at Dallas Rental Prices, Hidden Costs, and What Renters Need to Know Before Moving
June 2026
May 2026
You’ve got questions and we can’t wait to answer them.