Market Update Los Angeles
Market Update Los Angeles

The Big Story

The stage is set for 2024 to look a lot different from 2023


Quick Take:
  • The Fed telegraphed that rate hikes are ending, and financial markets expect rate cuts in 2024, which will meaningfully reduce the cost of financing and increase home sales.
  • High mortgage rates continue to drive low home sales, which are down 15% year over year. However, low sales have caused inventory to build, which will benefit the 2024 market as demand increases.
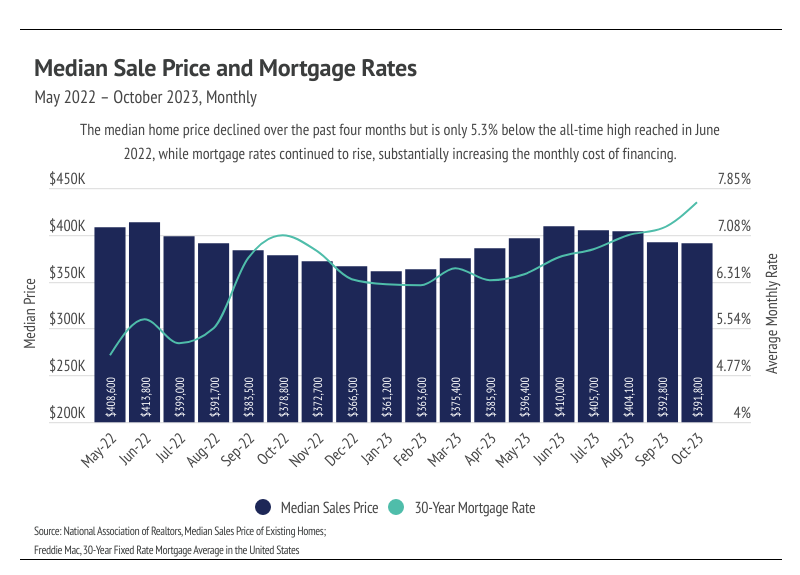
  • Home prices are declining slightly, which is normal this time of year, but mortgage rates are keeping the monthly cost of financing a home at or near record highs.


The 2024 housing market may not be flaming hot like in 2021, but it’ll definitely be a little spicy

Even though Fed Chair Jerome Powell remarked that it’s too soon to definitively conclude that rate hikes are finished, the financial markets have, in fact, decided they’re finished. As of December 4, 2023, interest-rate futures traders (the people who make a lot of money being right about where rates will go) expect the Fed to cut the federal funds rate, which currently falls between 5.25% and 5.50%, by 1.25%.
 
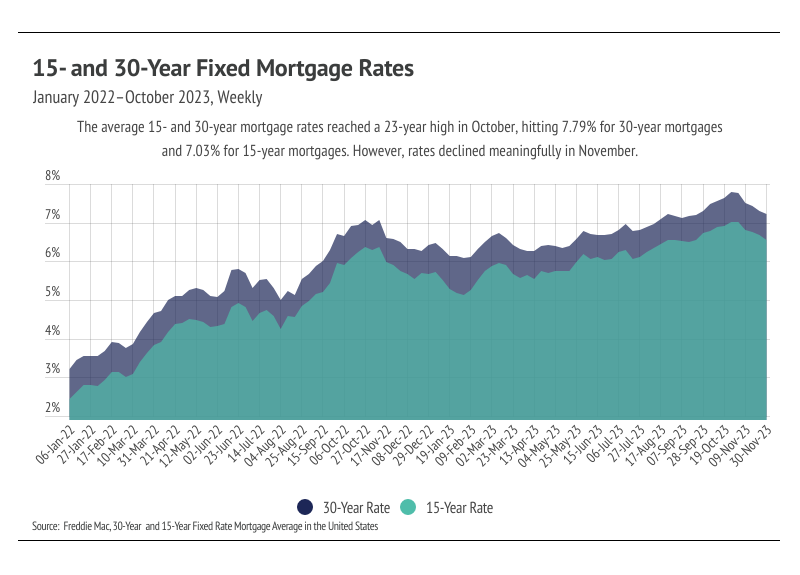
As a quick recap, the Fed dropped the fed funds rate effectively to 0% at the start of the pandemic and purchased mortgage-backed securities. The already historically low average 30-year mortgage rate then fell even further, reaching a record low of 2.65% in early 2021, which fueled the housing boom from June 2020 to June 2022. Inflation spiked in 2021, hitting levels not seen since the early 1980s and causing the Fed to begin rate hikes in March 2022, which trickled through markets quickly. From the beginning to the end of 2022, mortgage rates more than doubled, ending the white hot housing market and creating the slow-paced 2023 market. Mortgage rates continued to rise in 2023, hitting a 23-year high of 7.79% in October. Luckily, the average 30-year mortgage rate contracted in November 2023, falling to 7.22% by the end of the month.
 
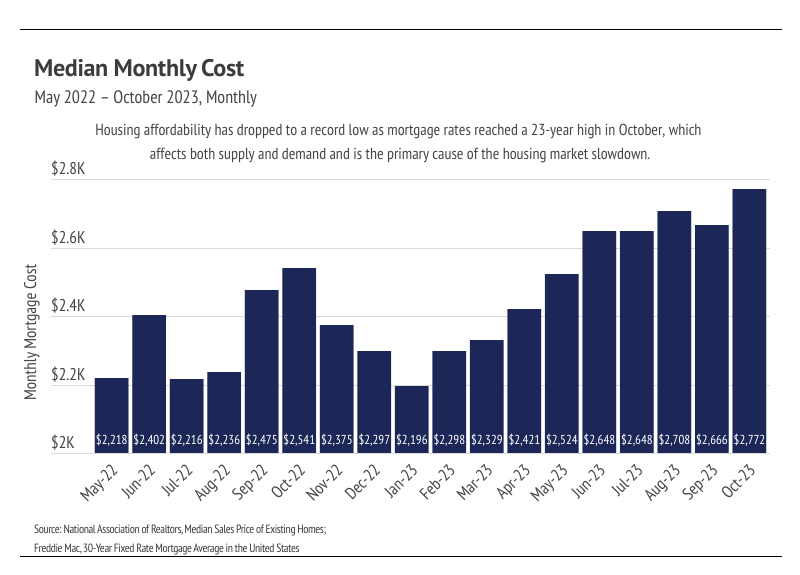
It’s hard to convey the full significance of higher mortgage rates on the housing market but, in short, they are the primary driver of the market slowdown. This is evidenced by the fact that the market began slowing down at almost the exact same time that the Fed began their rate hikes. In October 2023, a buyer’s monthly cost reached an all-time high when accounting for the cost of financing a mortgage. Redfin reported the highest rate of buyers backing out of home purchases on record, as home buyers experienced the sticker shock of the cost to finance the home. It should come as no surprise that sales continued to fall and will likely continue to decline through the winter months.
 
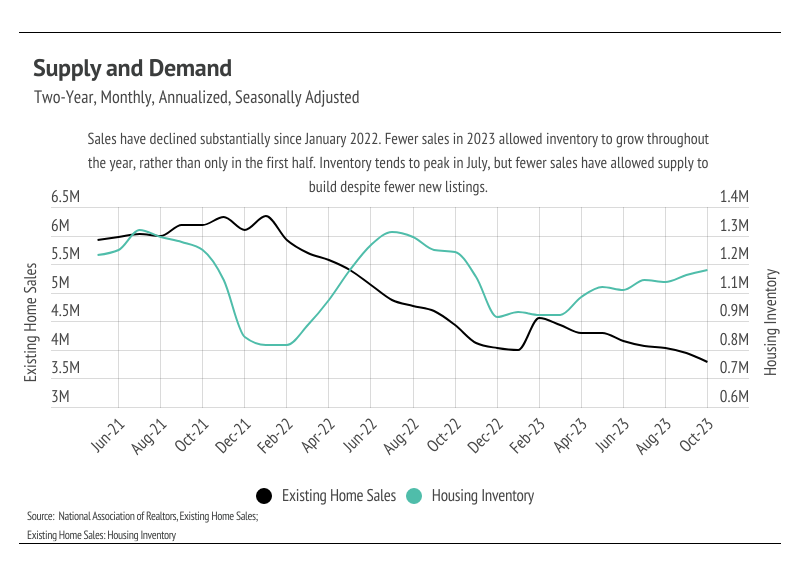
Now, back to our outlook for the year ahead. The falling sales in 2023 have allowed inventory to grow, which is much needed. Although inventory is still down 6% year over year, it has increased 20% in 2023 and will likely continue to increase through the rest of the year, which is far different from the typical seasonal trend of increasing in the first half of the year and declining in the second. In Q1 2024, we expect inventory to rise further, helping ease the low supply problem. Greater supply will be necessary because mortgage rates should decrease meaningfully with the anticipated rate cuts, driving up demand. A 1% decrease in interest rate equates to a 10% decrease in monthly financing costs. At this point, we expect a large number of would-be buyers to wait a little longer to gain more clarity around rate cuts in 2024 and hit the market in the spring and summer months.
 
Different regions and individual houses vary from the broad national trends, so we’ve included a Local Lowdown below to provide you with in-depth coverage for your area. In general, higher-priced regions (the West and Northeast) have been hit harder by mortgage rate hikes than less expensive markets (the South and Midwest) because of the absolute dollar cost of the rate hikes and limited ability to build new homes. The National Association of Realtors’ Chief Economist Lawrence Yun recently remarked that multiple offers are still occurring, especially on starter and mid-priced homes, even as price concessions are happening in the upper end of the market. As always, we will continue to monitor the housing and economic markets to best guide you in buying or selling your home.
 

Big Story Data

Chart of Dallas-area median sale prices and 30-year mortgage rates from May 2022 to October 2023.Bar chart of monthly mortgage costs, rising from $2,218 in May 2022 to $2,772 in October 2023.

Chart of weekly 30-year and 15-year fixed mortgage rates from January 2022 to October 2023.Line chart showing existing home sales declining and housing inventory rising overall from June 2021 to October 2023.

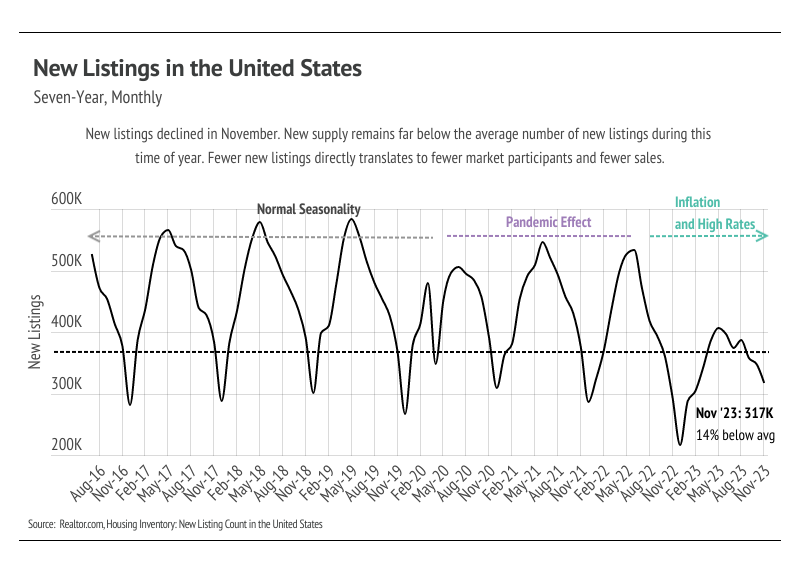
Chart of U.S. monthly new listings from 2016 to 2023, showing November 2023 below average.

The Local Lowdown

Quick Take:
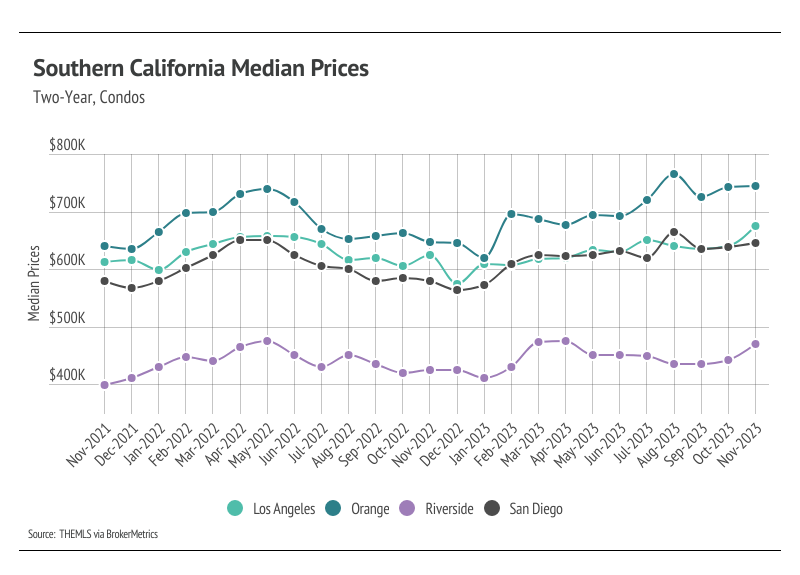
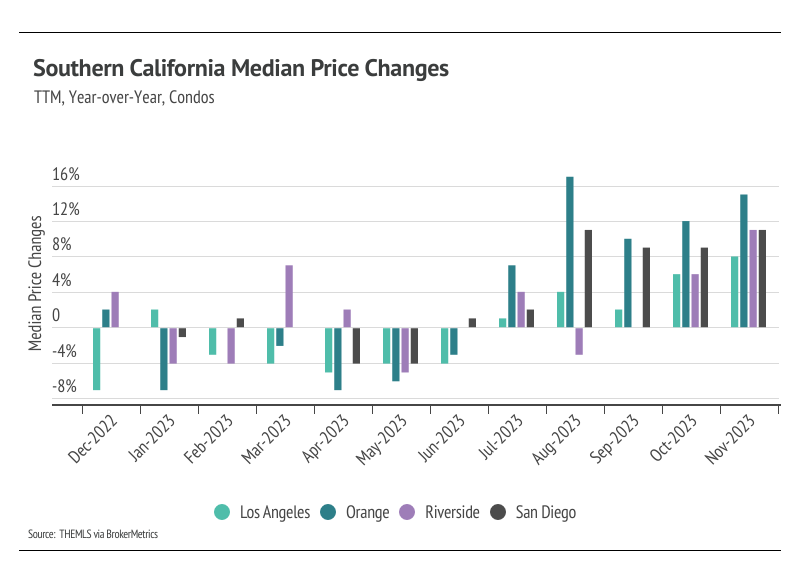
  • Median home prices are slightly below peak levels across Southern California, with the exception of Los Angeles condo prices, which reached a record high in November. We expect prices to remain fairly stable in the winter and to reach new highs in the spring.
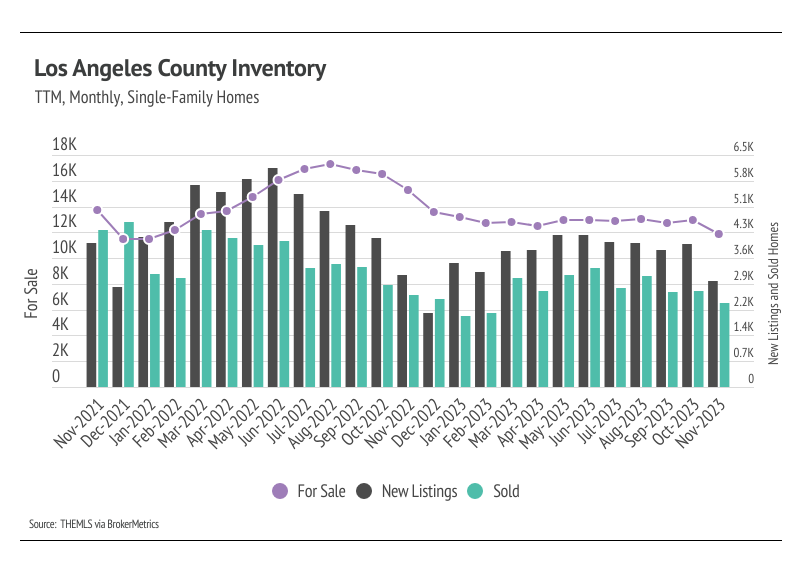
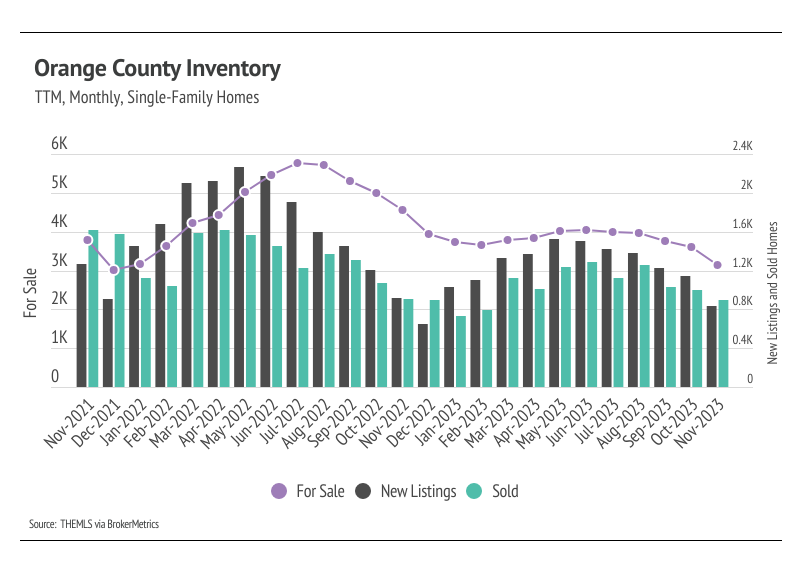
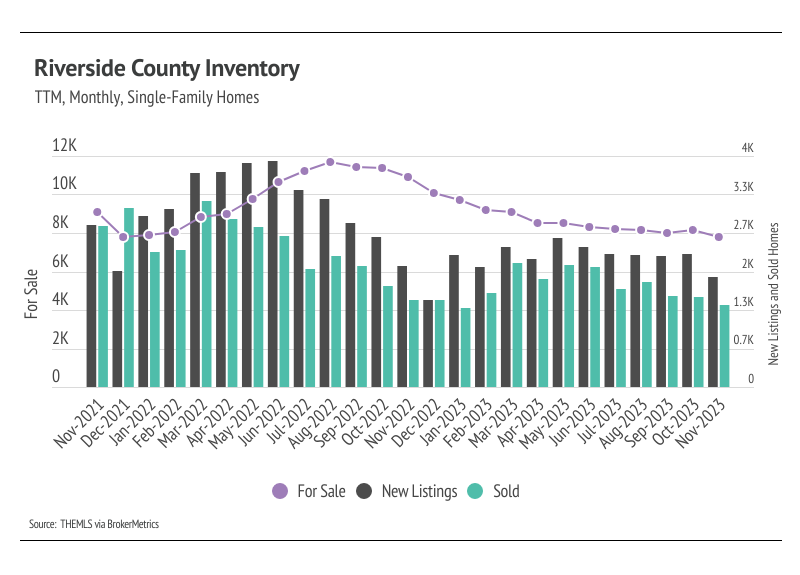
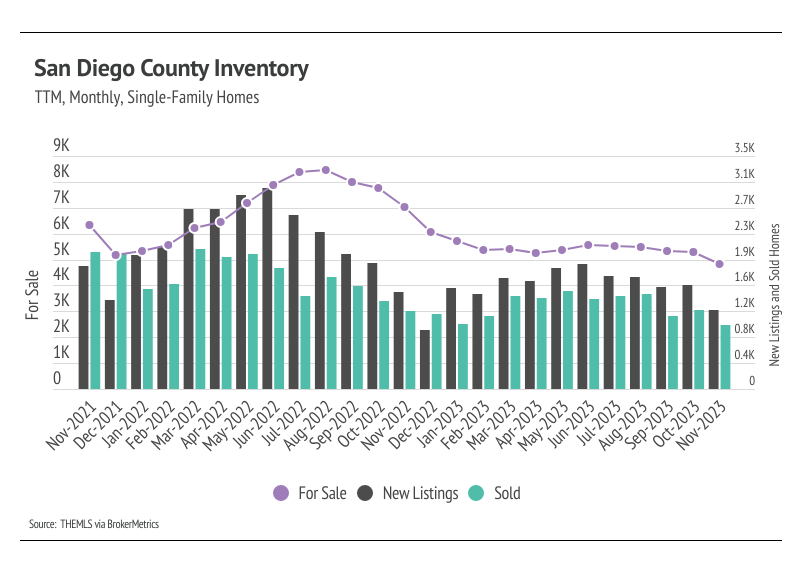
  • Active listings in Southern California fell month over month, continuing the 15-month downward trend, with single-family home inventory falling to a record low. Inventory will likely hit all-time lows across counties in the coming months as the number of new listings continues to fall.
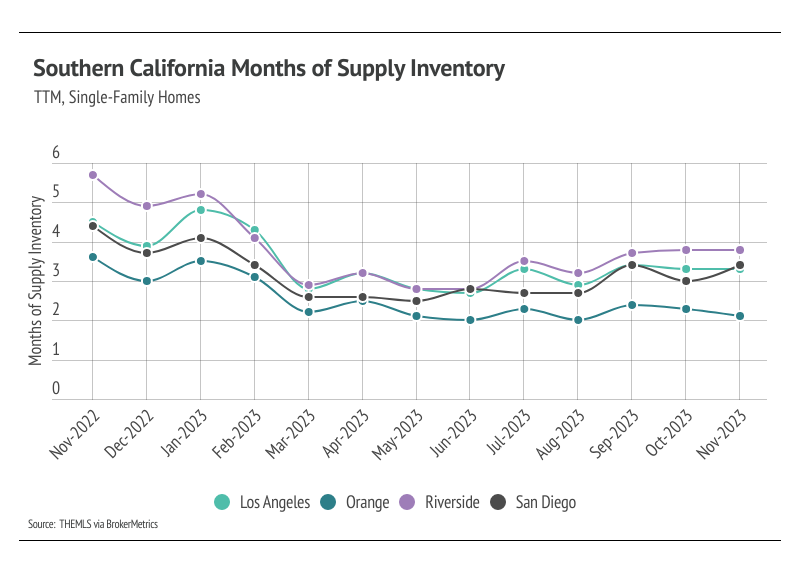
  • Months of Supply Inventory in November indicates a balanced market in Los Angeles, Riverside, and San Diego counties, while Orange County MSI indicates a sellers’ market. It’s typical for the market to become more balanced in the fall and winter, with fewer buyers participating.


Prices remain near record highs


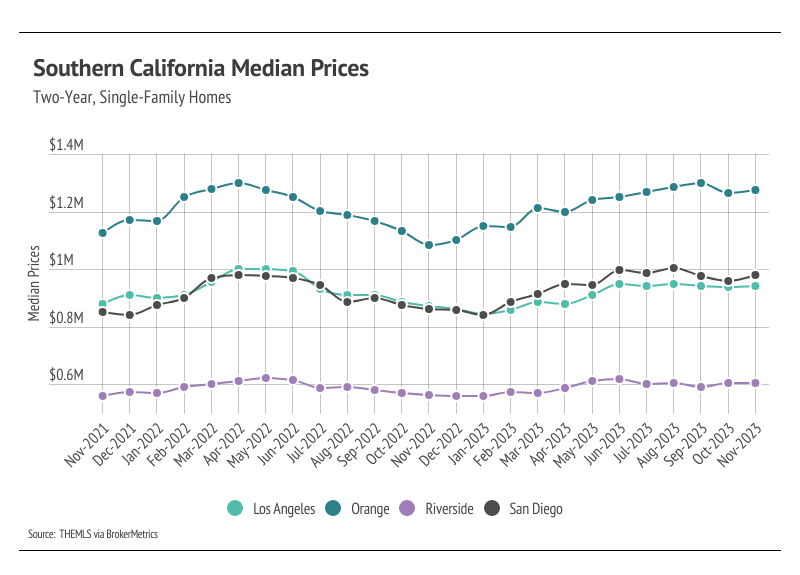
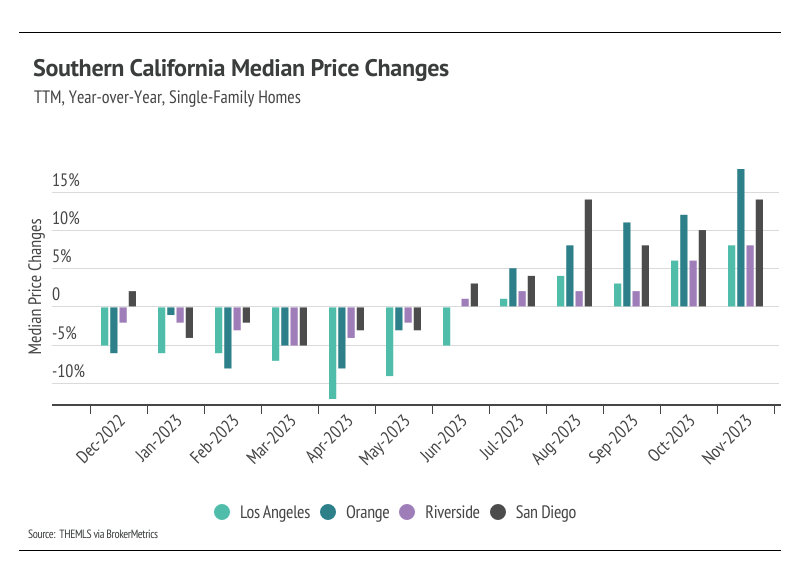
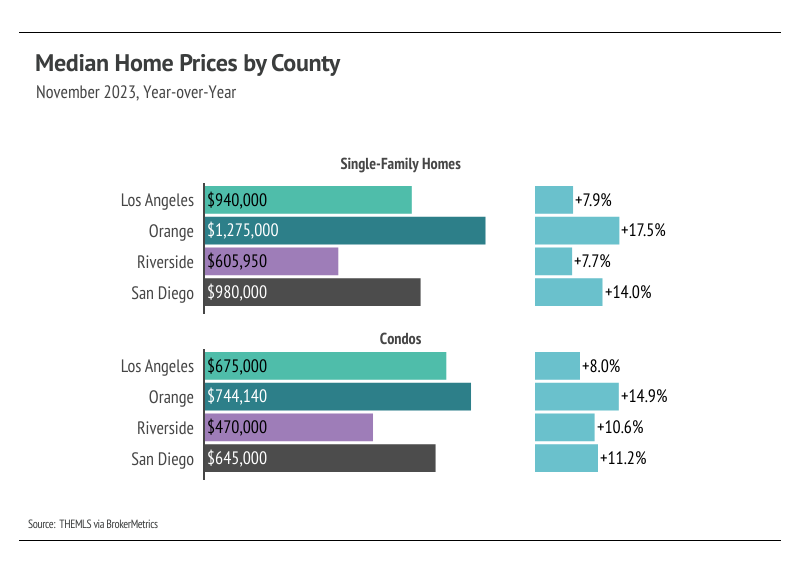
In Southern California, the home prices seem to be impervious to rising mortgage rates, even hitting all-time highs in recent months. The median San Diego prices for single-family homes and condos reached new all-time highs in August 2023. Orange County single-family home prices reached a new record in September 2023. In November, the median single-family home prices were only slightly below their peaks. Similarly, condo prices are near all-time highs with the exception of Los Angeles County condos, which reached a new high. Broadly, we expect prices to remain slightly below peak in the winter months, but as interest rates decline, prices will almost certainly reach new highs in the first half of 2024. Additionally, the sustained downward inventory trend and low number of new listings will only raise prices as demand grows. However, more homes must come to the market in the spring and summer to get anything close to a healthy market.
 
High mortgage rates soften both supply and demand, so ideally, as rates fall, far more sellers will come to the market. Rising demand can only do so much for the market if there isn’t supply to meet it. Unlike 2023, 2024 inventory has a much better chance of following more typical seasonal patterns.
 

Inventory continues 15-month downward trend, nearing record lows


Single-family home and condo inventory have trended lower over the past 15 months, which is far from the seasonal norm. Typically, inventory peaks in July or August and declines through December or January. In 2023, inventory didn’t have anything resembling the typical sine wave, since far fewer sellers came to the market, especially in the first half of the year. With inventory near historic lows in Southern California, and actually hitting an all-time low for single-family homes in San Diego in November, the number of new listings coming to market has become a significant predictor of sales. Month over month, new listings fell 22% and sales declined 11%. Year over year, sales and new listings are down 6% and 5%, respectively.
 
As demand slows, buyers are gaining slightly more negotiating power and paying less than asking price on average. The average seller received 94% of list in January, which grew to 99% by July. The amount sellers are receiving declined over the past four months, and in November 2023, the average seller received 97% of list. Inventory will almost certainly remain historically low for the next few months, and buyer competition will ramp up meaningfully in the spring, which will create price support.
 

Months of Supply Inventory indicates a mix of balanced and sellers’ markets


Months of Supply Inventory (MSI) quantifies the supply/demand relationship by measuring how many months it would take for all current homes listed on the market to sell at the current rate of sales. The long-term average MSI is around three months in California, which indicates a balanced market. An MSI lower than three indicates that there are more buyers than sellers on the market (meaning it’s a sellers’ market), while a higher MSI indicates there are more sellers than buyers (meaning it’s a buyers’ market). MSI fell below three months in the first quarter this year and remained fairly stable from March to August. MSI jumped from August to November  in Los Angeles, Riverside, and San Diego, indicating the market is more balanced for single-family homes, while Orange County MSI fell, implying that market still favors sellers.


Local Lowdown Data

Line chart comparing monthly single-family home median prices in four Southern California counties, November 2021–November 2023.Chart of Southern California single-family home median price changes, showing year-over-year trends by county from December 2022 to November 2023.

Chart comparing two-year condo median prices in Los Angeles, Orange, Riverside, and San Diego through November 2023.Bar chart of year-over-year condo price changes across four Southern California regions, December 2022 to November 2023.

Chart of November 2023 median home prices and year-over-year changes by county for homes and condos.Los Angeles County monthly single-family home inventory chart, November 2021 to November 2023.

Orange County single-family home inventory chart comparing homes for sale, new listings, and sales, November 2021–November 2023.Riverside County single-family home inventory chart comparing homes for sale, new listings, and sales, November 2021–November 2023.

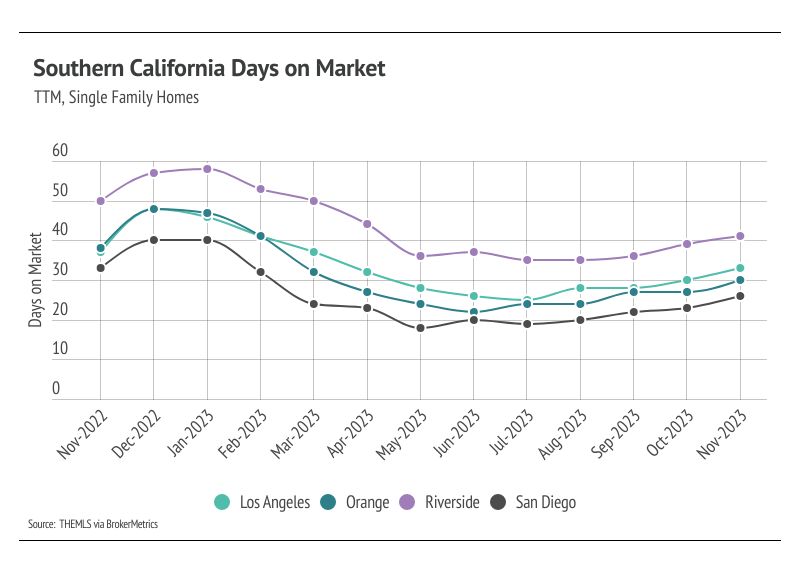
Chart of San Diego County single-family home inventory, new listings, and sales from November 2021 to November 2023.Line chart comparing days on market for single-family homes in four Southern California counties, November 2022–November 2023.

Line chart comparing months of housing supply in Los Angeles, Orange, Riverside, and San Diego, November 2022–November 2023.


Let's Talk

You’ve got questions and we can’t wait to answer them.